Download the Tabadulat app and start building your Shariah-compliant portfolio in minutes.
No. As of February 2026, Topgolf Callaway Brands (MODG) does not pass AAOIFI Shariah screening because interest-bearing investments and interest-bearing debt exceed the permitted limits. AAOIFI Standard No. 21 caps non-permissible income at 5% of revenue, and interest-bearing debt and investments at 30% of market capitalisation each. We re-screen monthly, so the status can change. Check the live verdict in the Tabadulat app.
Tabadulat re-screens Topgolf Callaway Brands (MODG) every month. Each review applies AAOIFI Shariah Standard No. 21 to the latest financial data: business activity, non-permissible income, interest-bearing investments and debt, and preference shares. Our Shariah Supervisory Board oversees the process. Ratios move with the market, so a verdict can change. App users are alerted if a holding turns non-compliant.
Yes. Topgolf Callaway Brands's income from non-permissible sources stays below AAOIFI's 5% ceiling in the February 2026 screening. The screen covers interest, conventional finance, alcohol, gambling and tobacco. Small incidental amounts are allowed, but they must be purified: investors donate that share of dividends to charity. We re-check this screen every month.
No. In the February 2026 screening, Topgolf Callaway Brands's interest-bearing investments are above AAOIFI's 30% market-capitalisation limit, so this screen currently fails. The ratio moves with the share price as well as the balance sheet. We re-screen every month, and the result can change.
No. In the February 2026 screening, Topgolf Callaway Brands's interest-bearing debt is above AAOIFI's 30% market-capitalisation cap, so this screen currently fails. Market capitalisation changes daily, so the ratio can improve or worsen without new borrowing. We re-screen every month, and the status can change.
No purification factor applies to Topgolf Callaway Brands (MODG) right now. Factors are published only for stocks that pass AAOIFI screening, and MODG currently does not. Purification (Tazkiyah) means donating the small impure share of dividend income to charity. If MODG returns to compliance in a monthly review, its factor is published again.
Yes. Topgolf Callaway Brands has no impermissible preference share structure, so it passes this AAOIFI screen as of February 2026. Preference shares promise holders fixed or priority dividends ahead of ordinary shareholders. That conflicts with the Shariah principle of sharing profit and loss in proportion to ownership. The screen is verified in every monthly review.
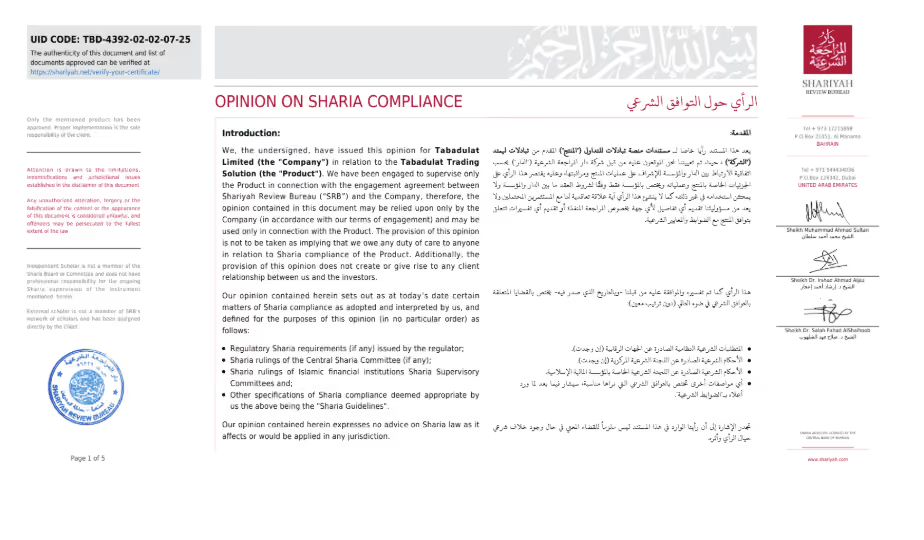
Screening follows AAOIFI Standard and overseen by our Shariah Supervisory Board.
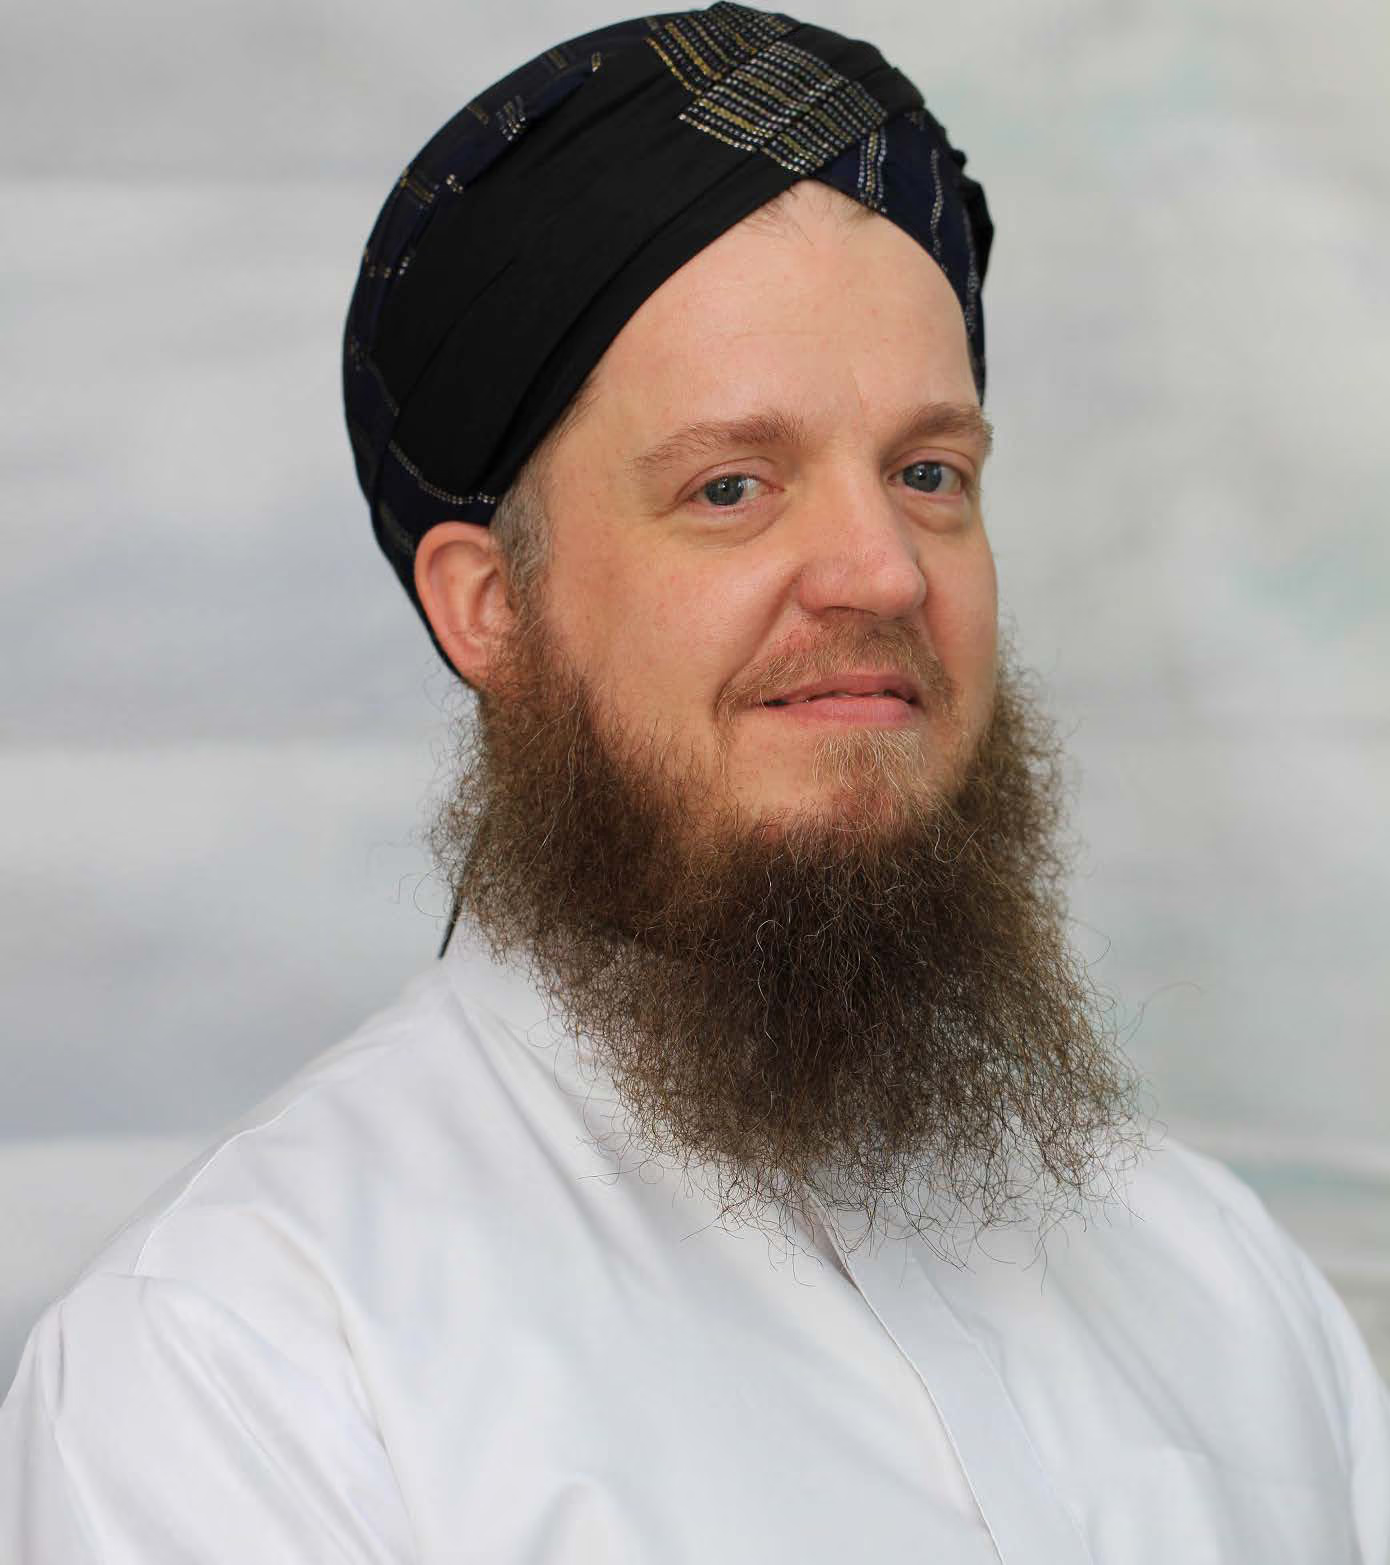
Masters (A'alamiyah) in Fiqh and Usool ul Fiqh, Jami'ah Ahsan Ul Uloom
Over 15 years as a Shari'a consultant across retail and investment banking, corporate advisory and real-estate funds, working with leading global and domestic institutions across the GCC. Sharia Advisor for UBAF France and a Shariah Supervisory Board member for CBI Al Islami and Rusd Capital in Dubai.
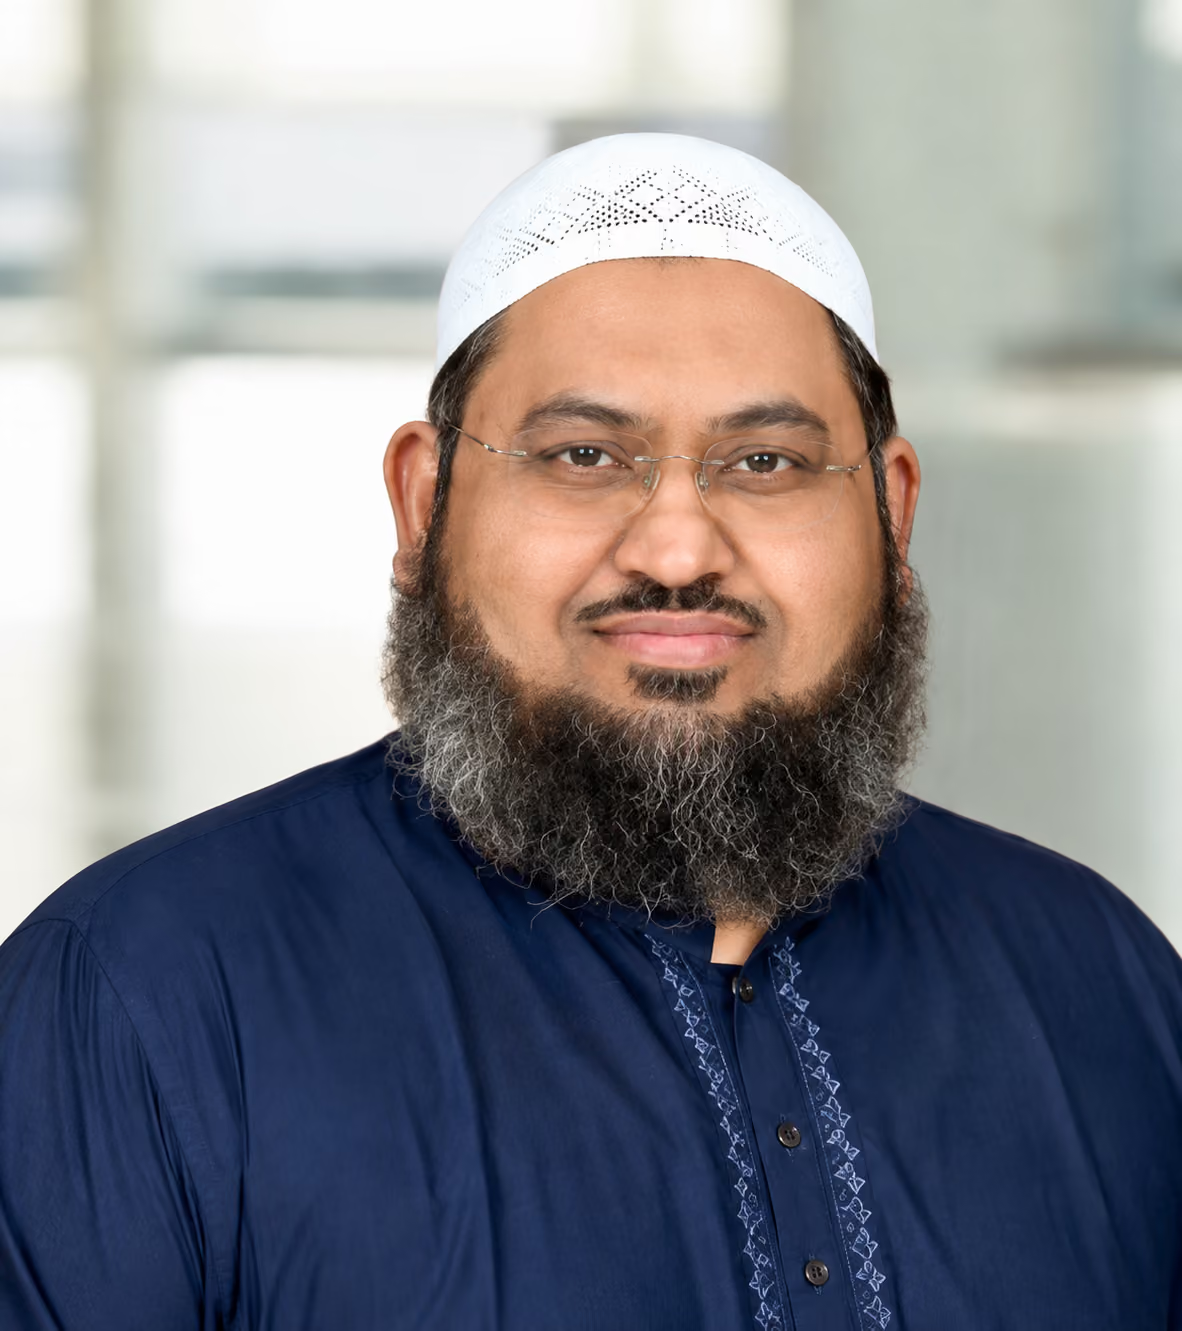
Takhassus in Ifta and Ph.D., Jamia Dar-ul-Uloom
Chairman of the Shariah Advisory Committee of the State Bank of Pakistan and Shariah Board Chairman of BankIslami Pakistan. He leads the Committee for the Review of AAOIFI Shari'ah Standards on Mudarabah and the Task Force for Islamic Alternatives for Agricultural Finance.
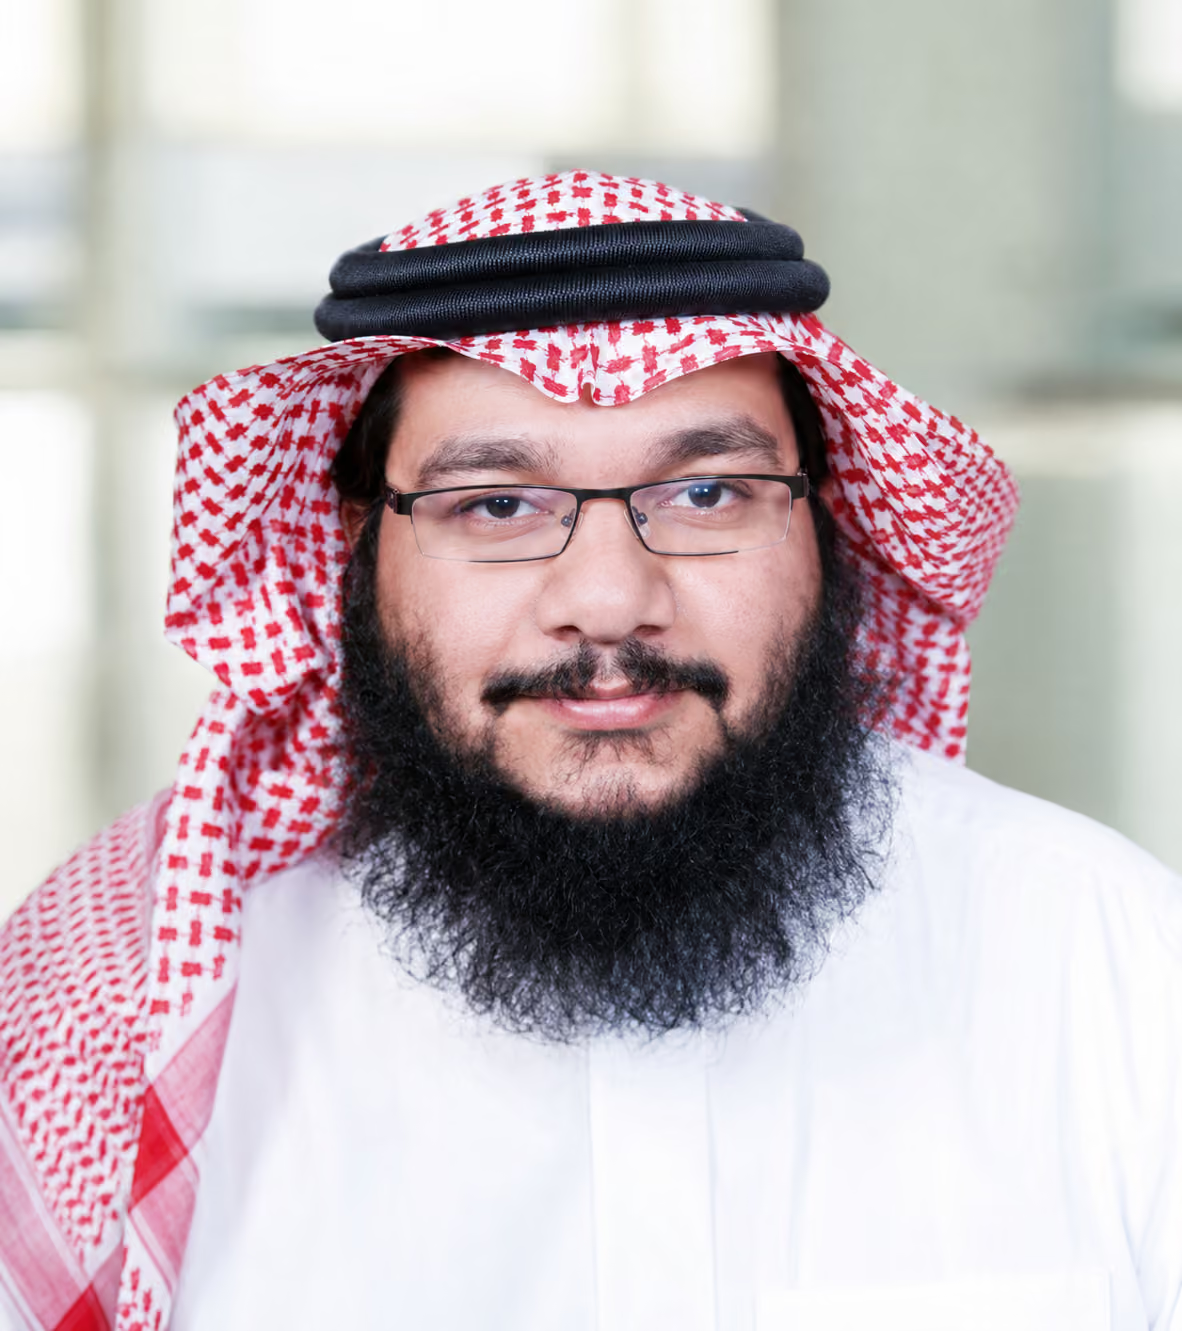
Ph.D. in Islamic and Middle Eastern Studies, University of Edinburgh
Assistant Professor at King Fahd University of Petroleum and Minerals, with engagements across the US, Europe and the GCC covering Sukuk, listed securities, Islamic insurance, home mortgages and private equity funds.
Masters in Fiqh and Usool ul Fiqh • 15+ years in GCC Islamic finance
Ph.D., Jamia Dar-ul-Uloom • Chairman, Shariah Advisory Committee, State Bank of Pakistan
Ph.D., University of Edinburgh • Assistant Professor, KFUPM