

Invest Halal, Anytime, Anywhere
Download the Tabadulat app and start building your Shariah-compliant portfolio in minutes.

Excellent 4.3 out of 5
Islamic savings with up to 6% expected profit p.a.
Grow your wealth with Shariah-compliant Murabaha savings plans, with up to 6% expected profit p.a. from assets you’re proud to own. T&Cs apply.

Regulated by ADGM FSRA
ADGM FSRA · Permission 250032
Shariah Supervisory Board
3 scholars oversee everything
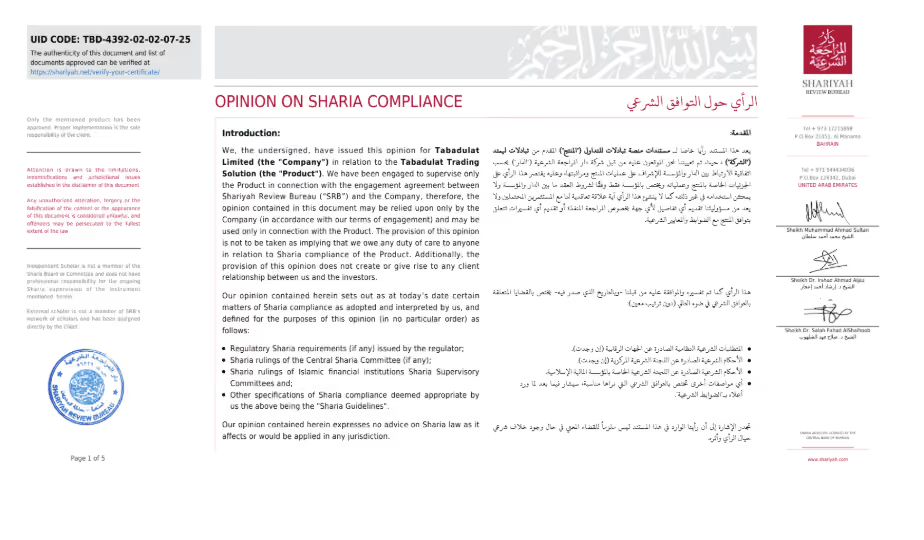
Certified fatwa
Download it anytime
Shariah Supervisory Board
3 scholars approve our Shariah methodology
Regulated by ADGM FSRA
ADGM FSRA. Permission 250032
How it works
Here's how to open a Murabaha savings plan with up to 6% expected profit p.a. from Shariah-compliant assets.
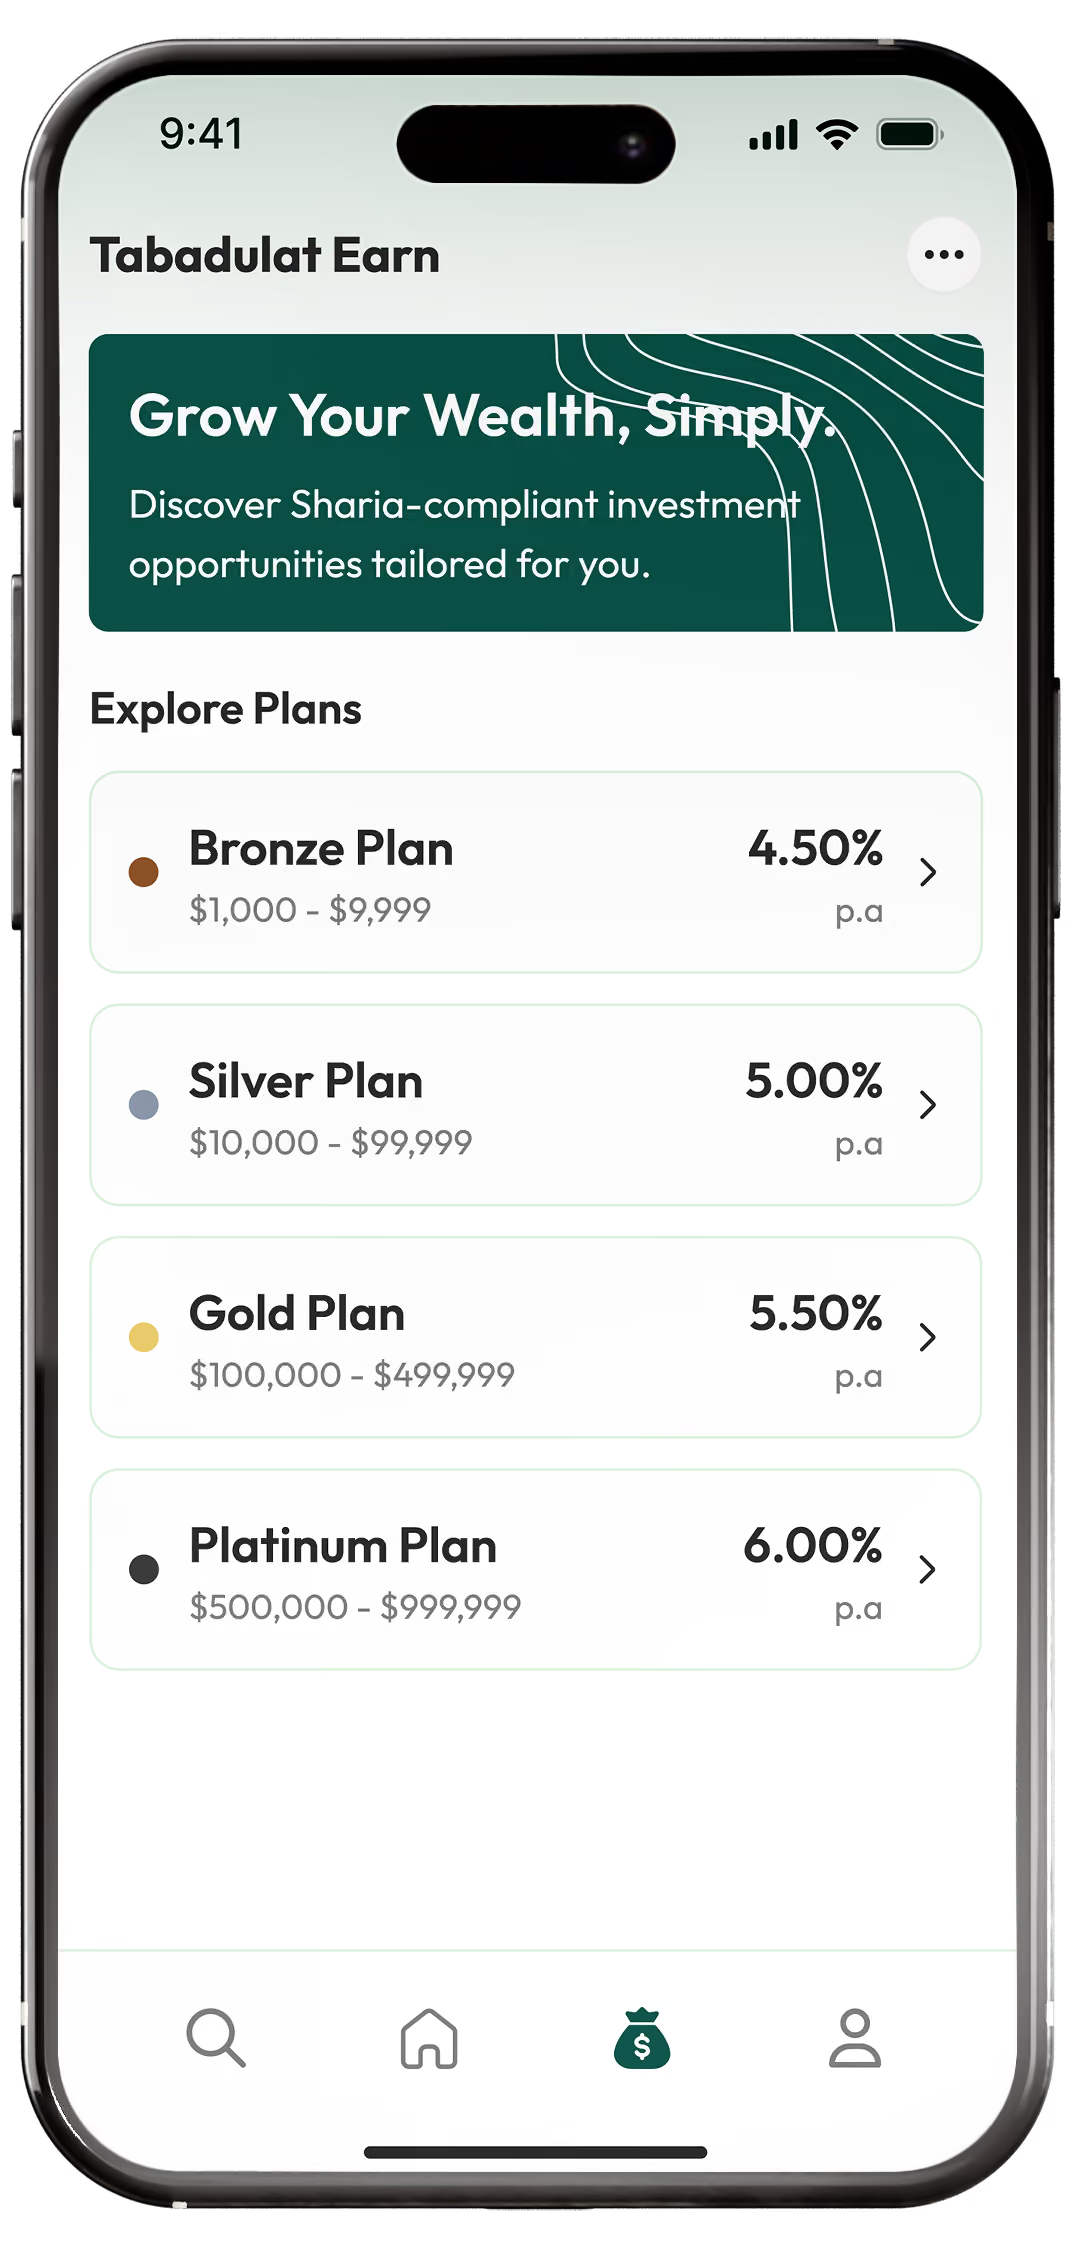
Pick your perfect savings plan
Pick a plan tier that works for your circumstance based on how long you’re happy to let your money work.
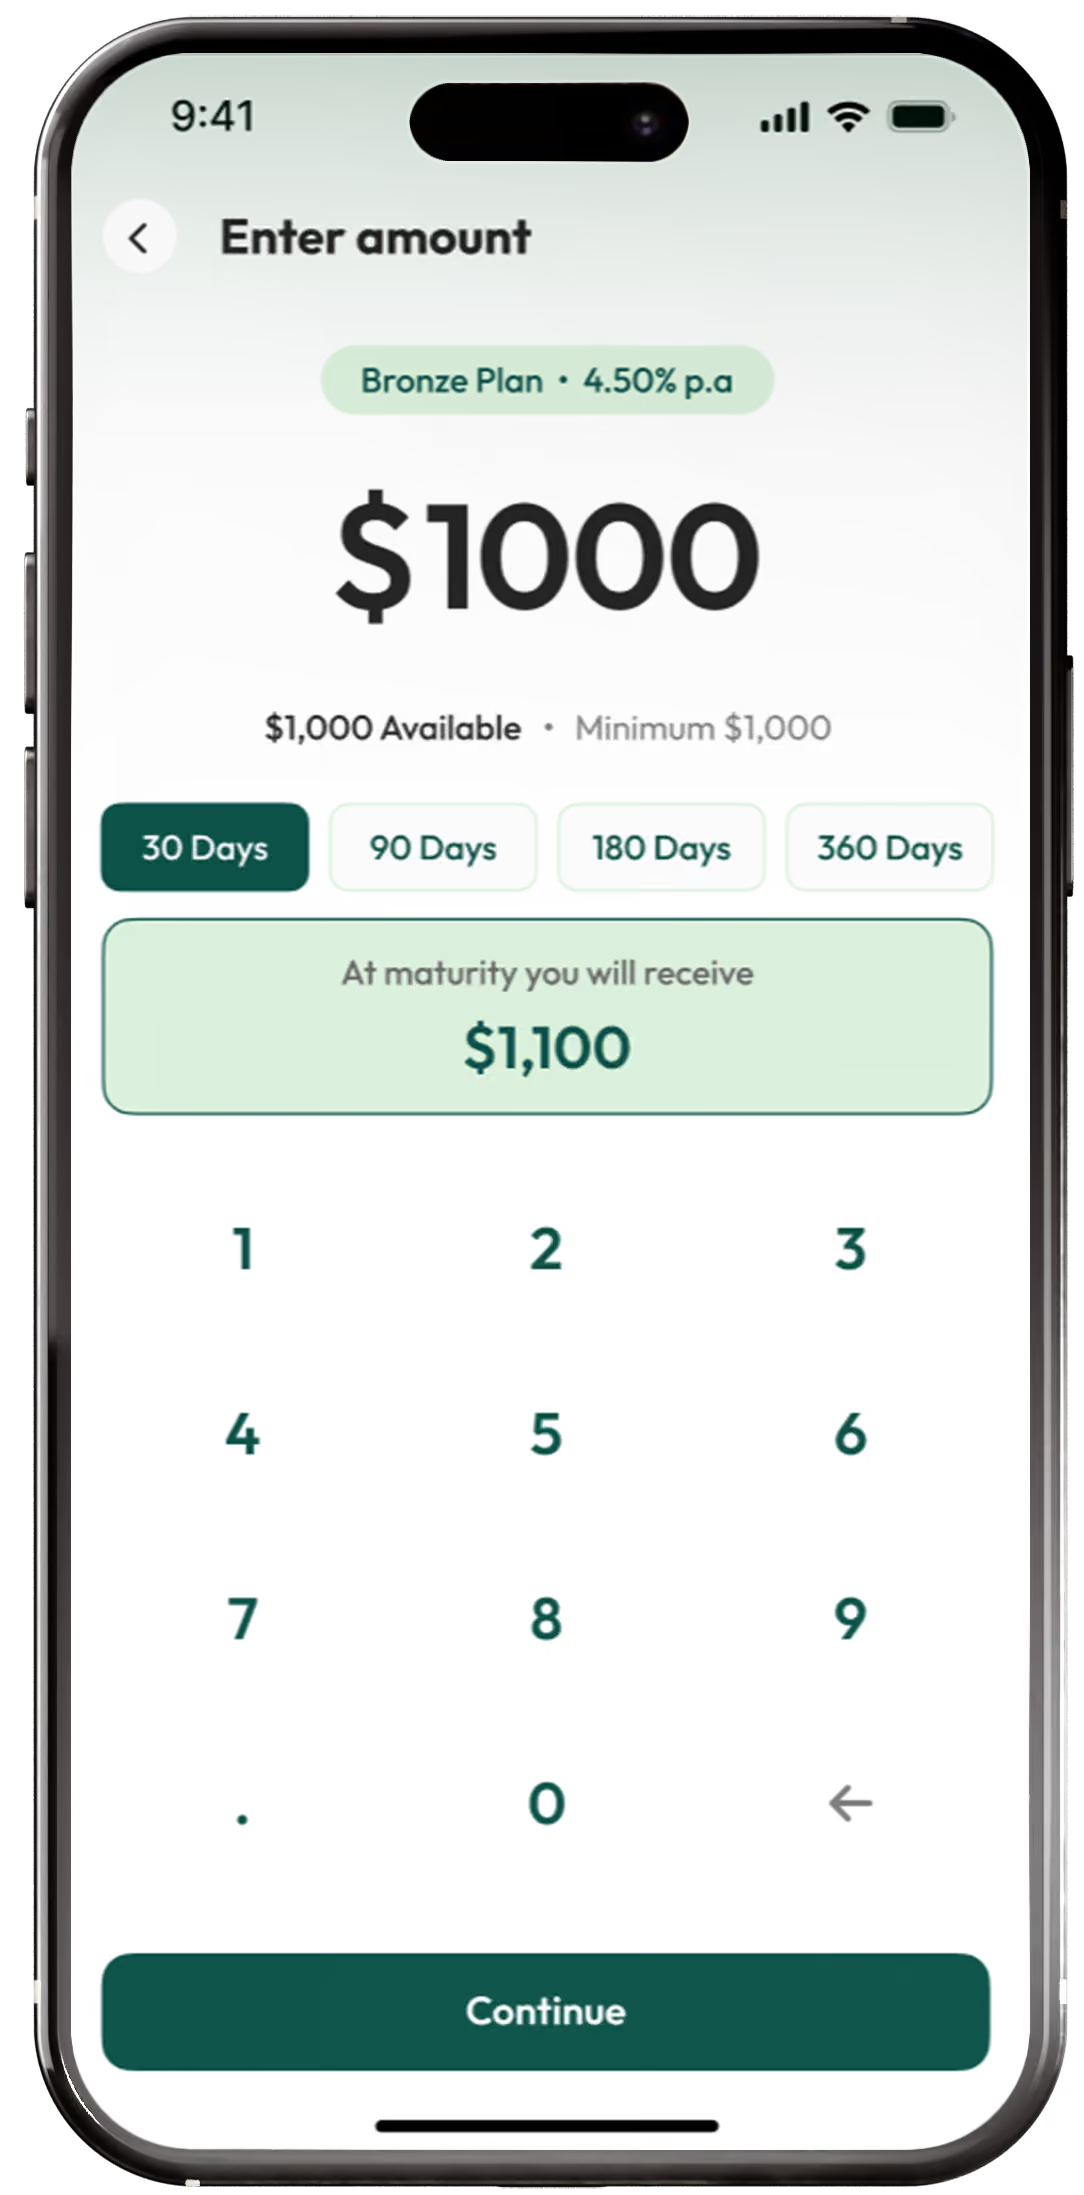
Decide the amount that will work for you
Decide how much you’re able to put to work towards your growth.
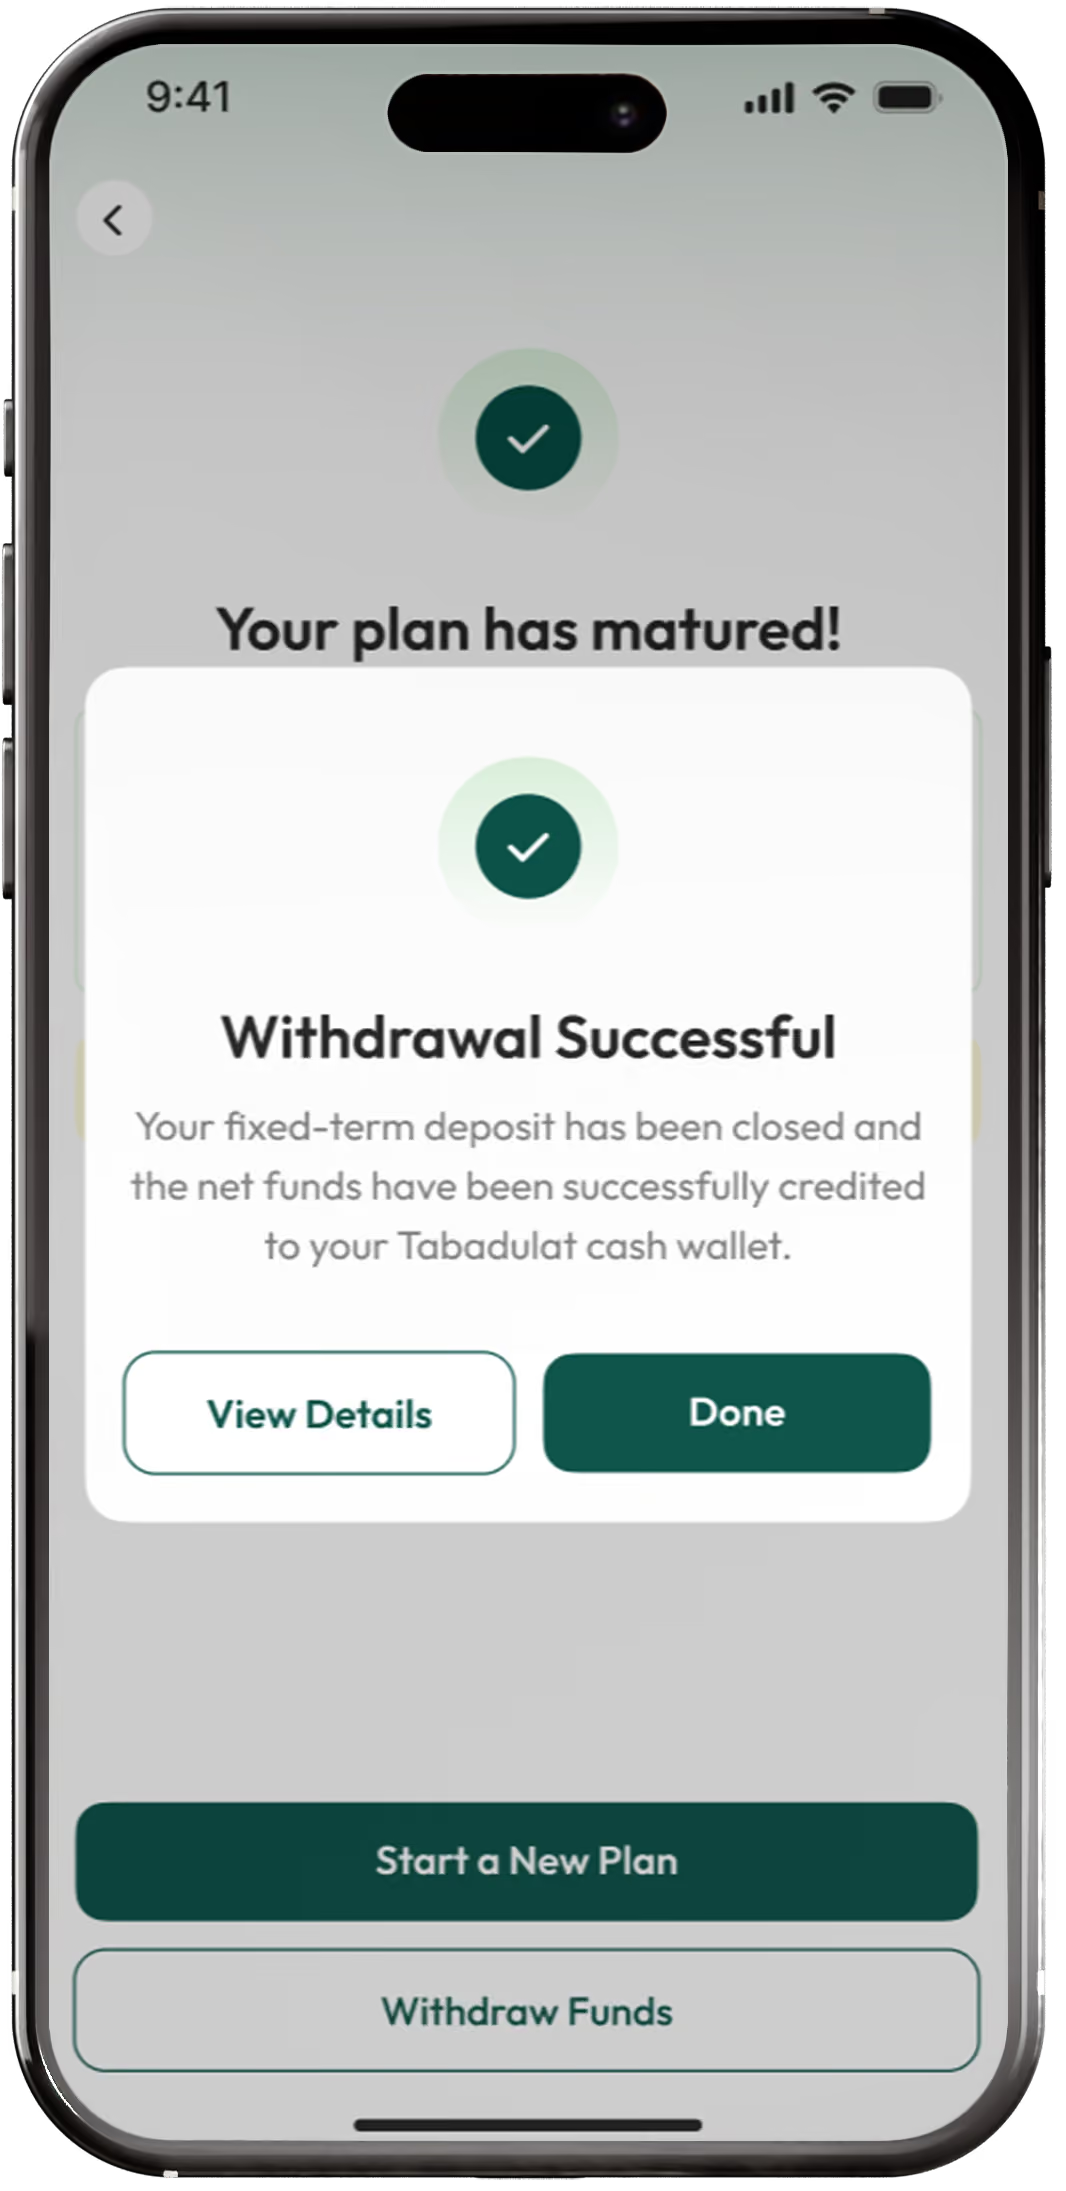
Watch it grow
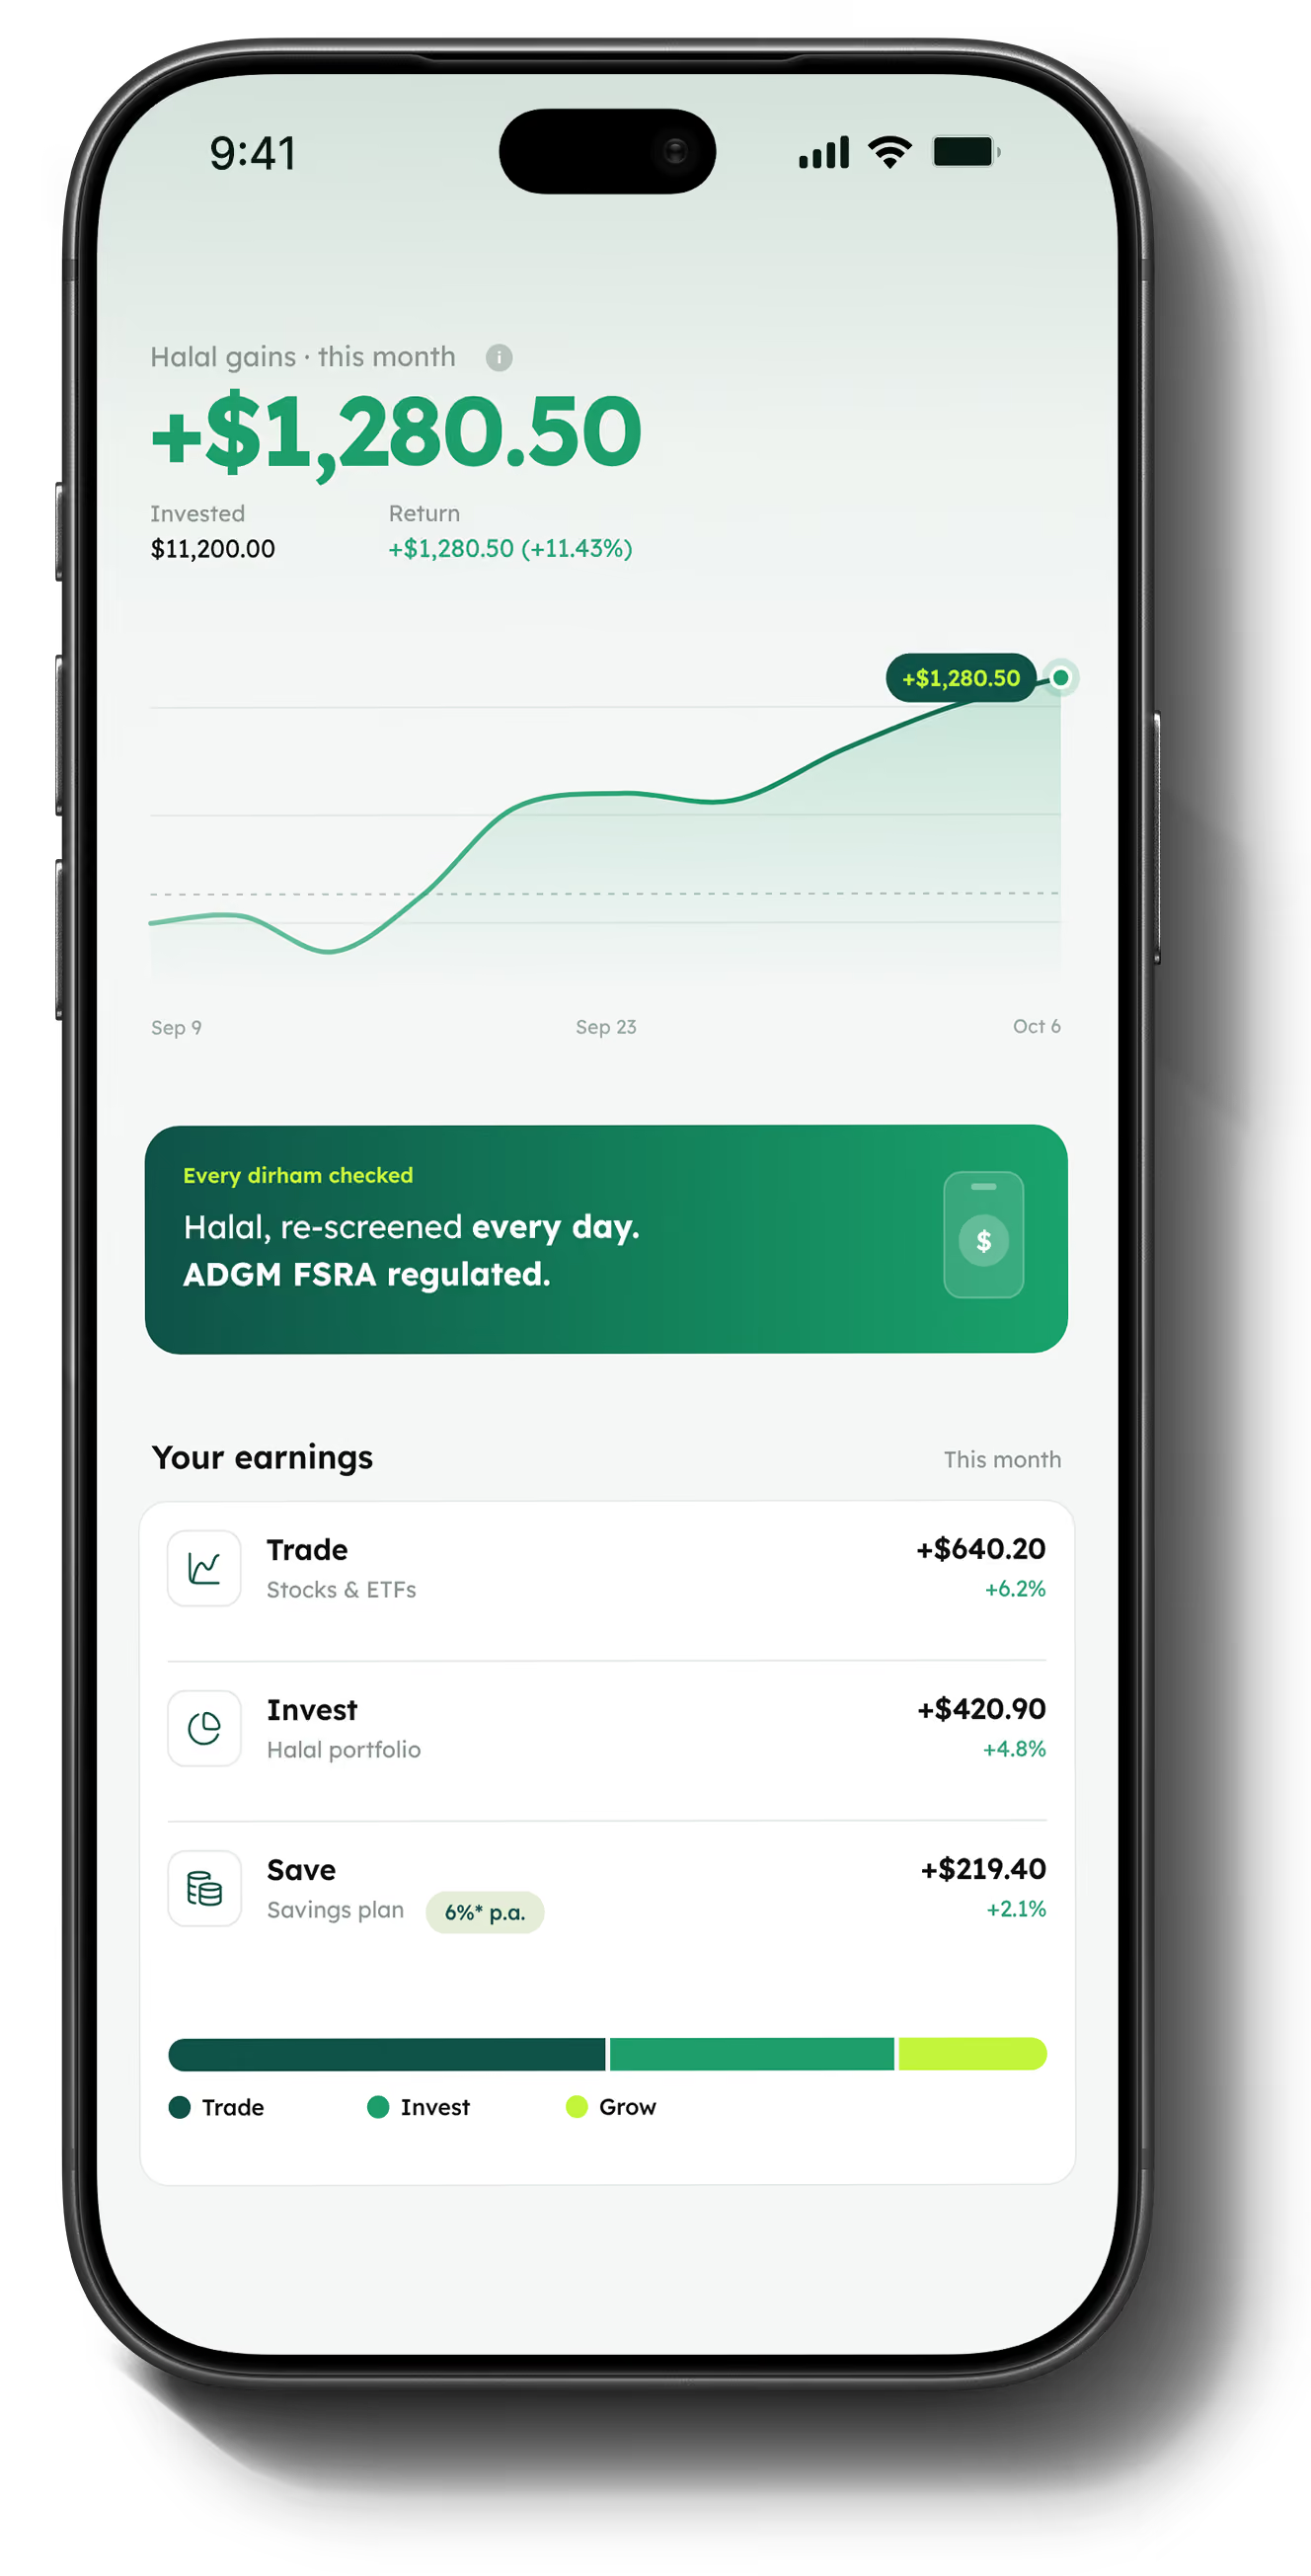
Track your Halal earnings. These earnings will only ever come from Halal trades and contracts. We re-check them everyday, because we’re just as invested in them staying Halal.
Start saving HalalFour plans. One Halal way to earn.
Whether you're starting with $1,000 or a larger amount, explore a savings plan that suits your goals.
Platinum
up to
6.00%
expected profit p.a.
Deposit: $500,000 to $999,999
Terms: 3, 6 or 12 months
No management fees eating into your expected profit.
Gold
up to
5.50%
expected profit p.a.
Deposit: $100,000 to $499,999
Terms: 3, 6 or 12 months
No management fees eating into your expected profit.
Silver
up to
5.00%
expected profit p.a.
Deposit: $10,000 to $99,999
Terms: 1, 3, 6 or 12 months
No management fees eating into your expected profit.
Bronze
up to
4.50%
expected profit p.a.
Deposit: $1,000 to $9,999
Terms: 1, 3, 6 or 12 months
No management fees eating into your expected profit.
Expected profit rates, agreed in your Murabaha contract and disclosed before you commit. As with any investment, capital is at risk. Tabadulat is not a bank. T&Cs apply.
We won’t let you invest in non-Shariah compliant assets
Licensed as an Islamic Financial Institution
By ADGM FSRA (No. 250032). Shariah compliance is part of our regulated activities.
Official AAOIFI Members
Tabadulat is a proud member of AAOIFI, the international standard-setting organisation for Islamic finance.
Shariah Supervisory Board
Our Shariah Supervisory Board oversees our products and operations to ensure we uphold Shariah principles at every stage.


Earn more
with Tabadulat
A savings account pays you a fraction of a percent. Tabadulat shares the profit from approved Murabaha plans.
0.01%
HSBC UAE
3%
WIO
4.2%
Sarwa
Up to 6% p.a.

Tabadulat
Rates as published by each provider on 22 October 2026 for UAE savings products. HSBC UAE, Wio and Sarwa figures are the interest or profit rates those providers advertise. Tabadulat’s figure is the expected profit rate on a 12-month Platinum Murabaha plan, agreed in your contract and not guaranteed. This is not a like-for-like comparison. Tabadulat is not a bank. T&Cs apply.
How Tabadulat Savings compares
Profit agreed before you deposit, no management fees and no salary transfer. See how it stacks up against the usual options.
Feature
Tabadulat Savings
Islamic bank savings
Halal money market funds
Profit known upfront
Tabadulat Savings
Yes, agreed upfront as an expected rate
Islamic bank savings
Typically expected/variable
Halal money market funds
Projected
Salary transfer required
Tabadulat Savings
No
Islamic bank savings
Often for highest rates
Halal money market funds
No
Management fee
Tabadulat Savings
0%
Islamic bank savings
Typically none
Halal money market funds
May apply
Promotional rate required
Tabadulat Savings
No
Islamic bank savings
Highest rates may be promotional
Halal money market funds
No
Choice of fixed terms
Tabadulat Savings
1, 3, 6 & 12 months
Islamic bank savings
Varies
Halal money market funds
No fixed term
Shariah-compliant structure
Tabadulat Savings
Commodity Murabaha
Islamic bank savings
Mudaraba/Wakala
Halal money market funds
Shariah-compliant fund
See what your money could earn. Halal.
Enter an amount, pick a plan and a term, and watch your expected profit* and your total at maturity update as you go. No riba, no management fees, and nothing to commit until you're ready.
How Murabaha works
What Our Users
Say About Tabadulat
Tabadulat is a reliable shariah compliant broker. It is actually regulated as both a broker and as an islamic business. It uses the real patent protected screening, no random "questionable" metrics or similar uncertainties from other unreliable screeners, and its free! Subhanallah. Finally the place a modern muslims can keep and grow his wealth.
S.M.UK
For me the best part is not having to second guess every company before investing. I can check the Shariah information directly and then decide from there. Makes the whole process a lot less stressful.
SaharDubai
My husband introduced me to this app when I was looking for an Islamic savings account and the murabaha product with Tabadulat paid much more than any other provider. I will definitely be recommending my family and friends do the same. It’s really easy to withdraw as well.
AasmaAbu Dhabi
I've been trading for many years and always had to compromise using conventional platforms to purchase shariah compliant stocks. But with Tabadulat, I can finally invest with the peace of mind that the entire brokerage, money movements, ethos, and methodology are shariah compliant. Really pleased with the product so far and exciting to see what they release next!
Ant.UAEIt’s almost 3 months since I used Tabadulat and I really enjoy my journey with them starting from the very simple app interface to the confidence of trading in ONLY halal assets
Salma H.UAEHuge relief!! First app I've used to trade without having to double triple check the sharia compliance first. Was a bit complex to deposit last month, but they keep making improvements, so I'm glad I was patient with it.
Saffana M.GB
Get answers to popular questions
Unlike other options, the more you know about Tabadulat, the more you’ll like us.
Other way to invest your money
Trade
Trade Halal stocks and ETFs.
Earn from price gains 0% commission on US stocks.
Learn moreEarn from price gains 0% commission on US stocks.

Invest
Build a portfolio from $1.
Build long-term wealth with a clear conscience through Shariah-Compliant Investment options.
Learn moreBuild long-term wealth with a clear conscience through Shariah-Compliant Investment options.
Earn
Up to 6% expected profit p.a.
Earn from Murabaha, agreed upfront. T&Cs apply.
Learn moreEarn from Murabaha, agreed upfront. T&Cs apply.

Got Questions?
We've Got Answers!
We're here to help! Reach out to us anytime, and we'll get back to you as soon as possible.
All questionsCan I withdraw early?


Each plan shows its early-withdrawal terms in the app before you commit. A Murabaha plan is a contract that runs to maturity, so if you break it early, the expected profit may be forfeited. T&Cs apply.
How is Murabaha different from interest?
Interest pays you for lending money, which is riba. Murabaha profit comes from a real trade: an asset bought and sold at a disclosed markup. You earn from commerce, not lending.
Is the profit guaranteed?
The expected rate is agreed in your contract at the start, which is what makes it a profit rate rather than interest. It is an investment, not a bank deposit: capital is at risk, and your funds sit segregated with regulated banks, separate from Tabadulat's own money. Tabadulat is not a bank. T&Cs apply.
What's the minimum?
$1,000 on the Bronze tier. Tiers run to $999,999 with terms of 1, 3, 6 or 12 months.
Who says it's halal?
Our Shariah Supervisory Board approves the structure, which follows AAOIFI standards, and our FSRA licence itself covers Shari'a-compliant regulated activities.
Clear conscience investing.
Keep your money working for you and keep your conscience clear with Tabadulat. Shariah-compliant portfolio.
Capital at risk.