



Is Pampa Energ�a (PAM) stock Halal?
Verdict for Pampa Energ�a (PAM): not Shariah compliant (FAIL). Screened October 2026 under AAOIFI Shariah Standard No. 21. Business activity: pass. Non-permissible income: pass. Interest-bearing investments: pass. Interest-bearing debt: fail. Preference shares: pass. Dividend purification factor: not applicable. Next review: November 2026.
Pampa Energ�a is a type of American Depository Receipt (ADR) representing shares in Pampa Energia a leading Argentine energy conglomerate. The primary purpose of this ADR is to enable American investors to invest in Pampa Energia's shares more conveniently, circumventing the complexities of directly investing in foreign markets. Pampa Energia operates mainly in the electricity and gas sectors, hence playing a crucial role in Argentina's energy landscape. For Muslim investors, though, the most pressing question is simpler: is Pampa Energ�a a Halal investment?
Is Pampa Energ�a Shariah compliant?
No. In the October 2026 screening Pampa Energ�a (PAM) does not pass AAOIFI screening: it fails the interest-bearing debt screen. Supplying power, gas or water is a permissible service, so utilities like Pampa Energ�a rarely trouble the activity screen. The pressure point is the balance sheet: grids and plants are among the most debt financed assets in any market, and AAOIFI Shariah Standard No. 21 caps interest bearing debt at 30% of market capitalisation, the screen that decides most utility verdicts.
Does Pampa Energ�a pass the business activity test?
The activity screen is only part of the picture this month: Pampa Energ�a currently fails the interest-bearing debt screen, so the overall verdict is not compliant regardless of the business itself. Delivering power or water raises no Shariah objection in itself; the scrutiny belongs to the debt behind the network.
Is Pampa Energ�a's income Halal?
Yes, within AAOIFI's tolerance. Pampa Energ�a's income from non-permissible sources stays below 5% of revenue in the October 2026 screening.
Does Pampa Energ�a meet AAOIFI's debt and investment ratio requirements?
Not in full. Interest bearing debt currently exceeds the 30% cap, measured against a market capitalisation of $4.18B (market data as of 1 October 2026), while the other ratio stays within it. One breach is enough to fail the screening; the ratios are reassessed monthly under our Shariah Supervisory Board.
Why do other halal screeners show a different verdict for Pampa Energ�a?
Screeners can disagree without either being wrong. AAOIFI Shariah Standard No. 21, which Tabadulat applies, measures interest bearing debt and investments against market capitalisation with a 30% ceiling. MSCI and FTSE measure them against total assets with a 33% ceiling, and S&P and Dow Jones Islamic use a multi year average of market capitalisation. Data dates differ too, because each provider reads filings and prices on its own schedule. The same company can therefore pass one standard and fail another in the same month. Tabadulat publishes one answer, the AAOIFI result as of October 2026, and re-screens it every month.
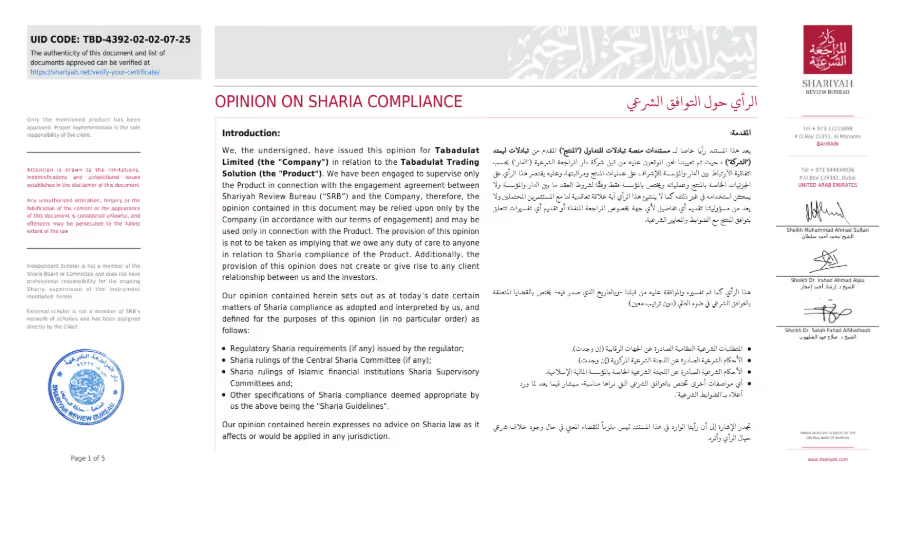
Tabadulat is an ADGM regulated brokerage whose license covers Shari'a Compliant Regulated Activities, as the FSRA permission names them. New to the terminology? Gharar and Maysir, Sukuk, Zakat and purification are all explained in plain English.
New to the screening method? Read What is Riba? A Clear Guide for Ethical Muslim Investing
Frequently asked questions
Is Pampa Energ�a (PAM) stock Halal to invest in?


How often is Pampa Energ�a (PAM) reviewed for Shariah compliance?
Does Pampa Energ�a (PAM) pass the AAOIFI non-permissible income screen?
Does Pampa Energ�a (PAM) pass the AAOIFI interest-bearing investments screen?
Does Pampa Energ�a (PAM) pass the AAOIFI interest-bearing debt screen?
What is the dividend purification factor for Pampa Energ�a (PAM) stock?
Does Pampa Energ�a (PAM) pass the AAOIFI preference share screen?